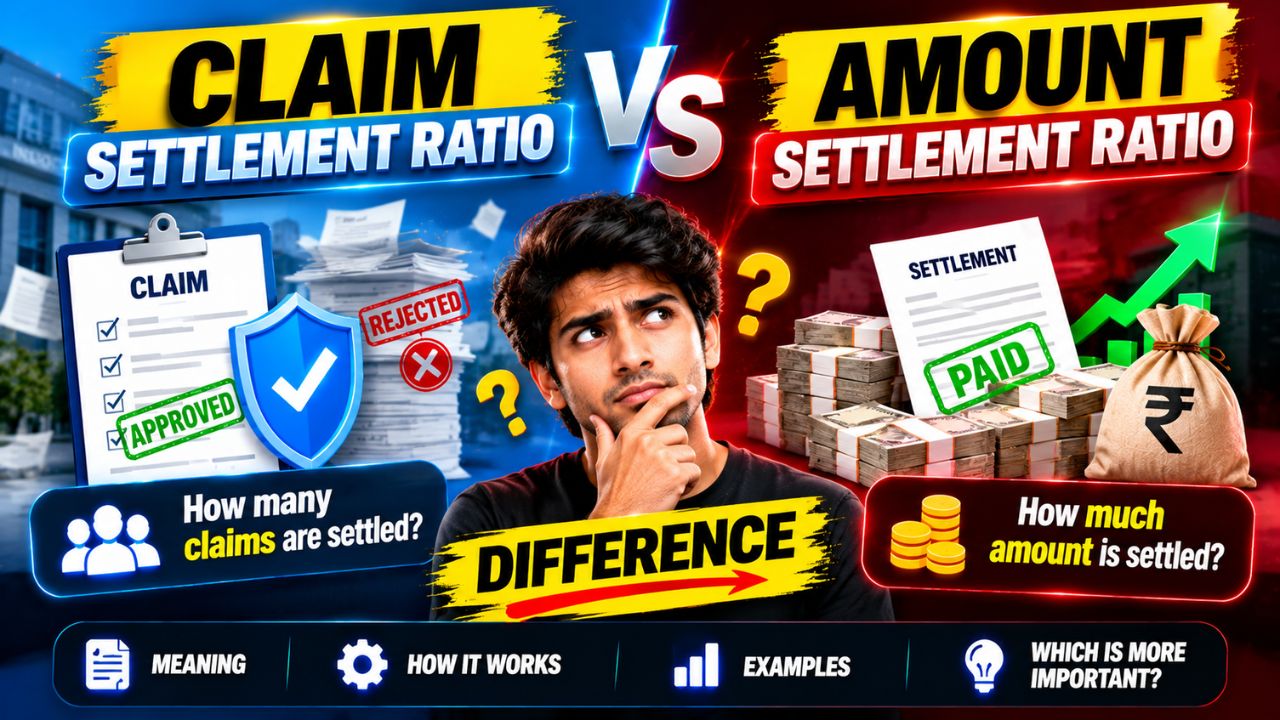
When buying life insurance, many people compare companies by looking at their Claim Settlement Ratio (CSR).
An insurer with a 99% ratio may appear to be a safer choice. But there’s another important metric you shouldn’t ignore: the Amount Settlement Ratio.
These two metrics measure different aspects of an insurance company’s claims performance. One focuses on the number of claims settled, while the other focuses on the monetary value of claims paid.
Understanding the difference can help you make a more informed decision when choosing a term insurance policy for your family.
What Is Claim Settlement Ratio?
The Claim Settlement Ratio measures the proportion of claims an insurance company settles compared with the total claims considered under the relevant reporting methodology during a financial year.
For example, suppose an insurer receives 1,000 claims and settles 990 of them. Its claim settlement ratio by number would be:
Claim Settlement Ratio = (Claims Settled ÷ Total Claims Considered) × 100
In this example:
(990 ÷ 1,000) × 100 = 99%
A higher ratio generally indicates that the insurer settled a larger proportion of claims by number. However, it doesn’t tell you how much money was paid for those claims.
What Is Amount Settlement Ratio?
The Amount Settlement Ratio measures claims performance based on money rather than the number of claims. It is commonly described as the claim settlement ratio by amount or value.
For example, if the total claim amount considered is ₹100 crore and the insurer pays ₹96 crore, the amount-based settlement ratio is 96%.
Amount Settlement Ratio = (Amount Paid for Settled Claims ÷ Total Claim Amount Considered) × 100
The exact calculation can depend on the reporting methodology and which claims or amounts are included in the denominator. When comparing insurers, use figures calculated on the same basis.
You can review the insurance industry’s reported claims figures in the IRDAI Annual Report 2024–25.
Claim Settlement Ratio vs Amount Settlement Ratio: Key Differences
| Comparison | Claim Settlement Ratio | Amount Settlement Ratio |
|---|---|---|
| Main focus | Number of claims settled | Monetary value of claims paid |
| Measures | Frequency of settlement | Value-based settlement performance |
| Example | 990 out of 1,000 claims settled | ₹96 crore paid out of ₹100 crore considered |
| Main advantage | Shows how often claims are settled | Shows how much of the claim value is paid |
| Limitation | Treats small and large claims as individual cases | Doesn’t show the number of claims settled |
| Best use | Evaluating claims performance by count | Understanding claims performance by value |
Both metrics provide useful information. Neither should be used alone to decide which insurer is best.
Example: Why Both Ratios Matter
Imagine two insurance companies with the following figures.
| Details | Insurer A | Insurer B |
|---|---|---|
| Total claims considered | 1,000 | 1,000 |
| Claims settled | 990 | 980 |
| Claim Settlement Ratio | 99% | 98% |
| Total claim amount considered | ₹100 crore | ₹100 crore |
| Amount paid | ₹90 crore | ₹97 crore |
| Amount Settlement Ratio | 90% | 97% |
In this simplified example, Insurer A has a higher claim settlement ratio by number. However, Insurer B has a higher amount-based settlement ratio.
This illustrates why looking only at the percentage of claims settled may not provide a complete picture.
Important: These figures are hypothetical and illustrate the difference between the two metrics. They are not actual insurer performance data, and the figures alone do not establish why the unpaid amounts differ.
Which Ratio Should You Check Before Buying Term Insurance?
If you’re buying term insurance, check both ratios rather than relying on a single headline percentage.
The Claim Settlement Ratio helps you understand the proportion of claims settled by number. The Amount Settlement Ratio adds another perspective by showing the proportion of the relevant claim value paid.
Before choosing a policy, consider these additional factors:
- Consistency over time: Review several years of claims data instead of relying on a single financial year.
- Number of claims: A percentage based on a small number of claims may be less informative than one based on a large claim volume.
- Claim rejection and repudiation data: Check the reported reasons and figures where available.
- Solvency ratio: This provides information about an insurer’s financial ability to meet its obligations, although it doesn’t guarantee the outcome of an individual claim.
- Policy terms and exclusions: Understand the coverage, exclusions and conditions that apply to your policy.
- Disclosure accuracy: Provide complete and truthful information about your health, occupation, income and other details requested in the proposal form.
You can also consult the official IRDAI website for regulatory information and insurance publications.
Is a 99% Claim Settlement Ratio a Guarantee That Your Claim Will Be Paid?
No. A 99% claim settlement ratio does not guarantee that every policyholder’s claim will be approved.
The ratio reflects an insurer’s reported claims experience under a particular methodology and during a specific period. The outcome of an individual claim depends on the policy’s terms, the facts of the case, applicable requirements and the documents submitted.
Likewise, a lower amount-based ratio does not automatically mean that an insurer unfairly rejects claims. Differences in claim sizes, reporting methods and the mix of claims can influence the figures.
Use these ratios as comparison tools, not as promises of future claim approval.
Final Verdict
The main difference between Claim Settlement Ratio and Amount Settlement Ratio is simple: CSR by number tells you how many claims were settled, while the amount-based ratio tells you how much claim value was paid.
For a more balanced assessment of a life insurance company, check both metrics, compare consistent data across multiple years and review the insurer’s financial strength and policy conditions.
Don’t select a term insurance policy solely because an insurer advertises a 99% claim settlement ratio. A careful review of the available data and the policy’s terms can help you make a better-informed choice for your family.