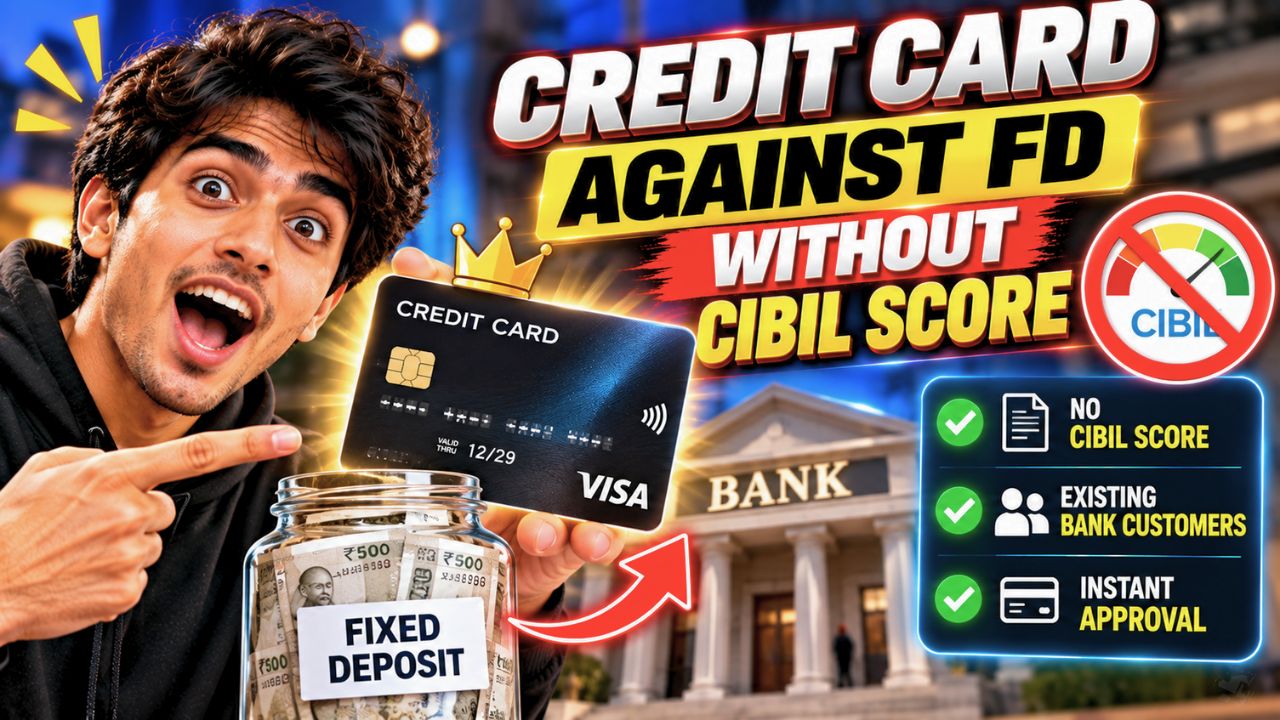
Getting rejected for a credit card because you have no CIBIL score? You may not need to wait months to build your credit history.
In India, several banks offer credit cards against a Fixed Deposit (FD), making them an option for first-time applicants and people with limited credit history.
Unlike regular credit cards, these cards are secured by your deposit. This reduces the lender’s risk and may make approval easier, even if you have no established credit score.
However, eligibility, minimum FD requirements and approval conditions vary by bank.
What Is a Credit Card Against FD?
A credit card against FD, also known as a secured credit card, is issued against a fixed deposit that you maintain with the bank. The FD acts as collateral, and the bank generally assigns a credit limit based on a percentage of the deposit amount.
For example, if you open an FD of ₹20,000 and the bank offers a credit limit of 90% of the deposit, your credit limit could be ₹18,000.
Your FD can continue earning interest while it is pledged as security. However, you usually cannot freely withdraw or close the pledged deposit until the card is closed and outstanding dues are settled, subject to the bank’s terms.
Best Credit Cards Against FD Without a CIBIL Score
Here are some options worth checking if you want a credit card without an established credit history.
1. Kotak811 Dream Different Credit Card
Kotak811 offers an FD-backed credit card designed for people who want to start their credit journey. Its official product page states that applicants can apply without a CIBIL score or income proof.
The listed minimum FD amount is ₹10,000. The bank also advertises rewards and cashback benefits, but eligibility conditions, fees and offer terms should be checked before applying.
Read the details on the official Kotak811 credit card page.
2. HDFC Bank Credit Card Against FD
HDFC Bank also offers a credit card secured by a fixed deposit. According to its published eligibility information, the minimum FD amount is ₹15,000, subject to the applicable tenure and other conditions.
This option may suit applicants who have limited credit history and are comfortable maintaining an eligible FD with the bank. Check the latest requirements before opening a deposit.
3. ICICI Bank Fixed Deposit Credit Card
ICICI Bank offers fixed deposit-backed credit cards, including its Instant Platinum and Coral variants. Its published requirements include a minimum FD of ₹50,000, a minimum tenure of 180 days and auto-renewal.
This option may be more suitable if you can maintain a larger deposit and meet the bank’s conditions.
Important: Minimum deposits, card variants, fees and approval policies can change. Compare the current terms directly with the issuer before applying.
How to Apply for a Credit Card Against FD
The application process is usually straightforward, although the exact steps depend on the bank.
- Choose a bank: Compare minimum FD amounts, credit limits, annual fees, rewards and other charges.
- Open an eligible FD: Create a fixed deposit with the issuing bank if you do not already have one that qualifies.
- Complete KYC: Keep your PAN, identity details, address information and other requested documents ready.
- Apply for the card: Use the bank’s official website, mobile app or branch, depending on the available application method.
- Link the FD as security: The bank may place a lien on the deposit, restricting withdrawal while it secures your card.
- Activate and use your card: Once approved, activate it and review the billing cycle, repayment date and applicable charges.
Having an FD can improve your chances, but it does not guarantee approval. Banks may still conduct identity verification and other internal checks.
Can You Get a Credit Card With No CIBIL Score?
Yes, it is possible. A credit card secured by an FD can be an alternative when you have never borrowed money or used a credit product that generated a credit history.
However, having no CIBIL score is different from having a poor credit score. If you have a history of missed payments or defaults, the bank may consider that information when evaluating your application.
A secured card can help establish a credit history when the issuer reports your account activity to credit bureaus. Results depend on the issuer’s reporting practices and how responsibly you manage the card.
How to Improve Your CIBIL Score Using an FD-Backed Credit Card
Once you receive the card, follow these habits to build a positive credit history over time:
- Pay your full bill on time: Avoid missed payments and unnecessary interest.
- Keep credit utilisation low: Try not to use most of your available credit limit every month.
- Avoid unnecessary applications: Applying for multiple credit products in a short period may not be helpful.
- Check your credit report: Review it periodically for errors and verify that your account is being reported correctly.
- Use the card responsibly: Small, planned purchases that you can repay in full are generally sufficient.
There is no guaranteed timeline for reaching a particular CIBIL score. Consistent repayment behaviour and the information reported by lenders influence your credit profile.
What Are the Risks of a Credit Card Against FD?
An FD-backed credit card can help you access credit, but there are a few things to understand before applying.
- Your deposit is at risk if you default. If you fail to repay your card dues, the bank may use the pledged FD to recover the outstanding amount, subject to the card agreement and applicable rules.
- Your credit limit may be lower than your FD. Banks typically offer only a percentage of the deposit as available credit.
- Fees may apply. Check joining fees, annual charges, interest rates, late-payment charges and other applicable costs.
- You still need to repay the bill. The FD is security, not a substitute for making your monthly payments.
Final Verdict
A credit card against FD without a CIBIL score can be a practical starting point if you are new to credit or have struggled to qualify for an unsecured card. Kotak811, HDFC Bank and ICICI Bank are options to compare, but their minimum deposit requirements and terms differ.
Before applying, choose a deposit amount you can comfortably lock in, read the bank’s fees and conditions, and use the card only for purchases you can repay. Responsible usage can help you establish a credit history without taking on unnecessary debt.